Demos
 Colors
 Docs
 Support




Filing your Income Tax Return is more than just a yearly compliance task. It is a crucial part of managing your financial health and staying on the right side of the law. Yet, many taxpayers in India tend to delay this responsibility until the last moment, often leading to stress, errors, or even penalties. Understanding the last date to file ITR in India and the consequences of missing it can help you make better decisions and avoid unnecessary complications.
This guide explains everything you need to know about the income tax return deadline, late filing penalties, and how professional tax filing services like LIT NEXUS can make the process simple and hassle free.
Understanding the Last Date to File ITR in India
The last date to file ITR in India typically depends on the category of the taxpayer. For most individual taxpayers, including salaried employees and freelancers who do not require audit, the deadline is usually 31st July of the assessment year. For businesses and individuals whose accounts require auditing, the deadline is generally extended to 31st October.
These deadlines are set by the Income Tax Department and are important to follow. Filing your return within the due date ensures that you stay compliant and avoid additional charges or complications. It also allows you to process refunds faster and maintain a clean financial record.
Who Needs to File Income Tax Returns
Many people believe that only those with high income need to file ITR, but that is not entirely true. In India, individuals whose income exceeds the basic exemption limit must file their returns. Apart from that, even if your income is below the taxable limit, filing ITR can be beneficial in several situations.
If you are a salaried employee, freelancer, business owner, or even an investor earning capital gains, you may be required to file your return. Additionally, filing ITR is essential if you want to claim a tax refund, apply for loans, or maintain proper financial documentation for future purposes.
What Happens If You Miss the ITR Filing Deadline
Missing the income tax return deadline can lead to several consequences that go beyond just a late fee. Once the due date passes, you can still file a belated return, but it comes with certain drawbacks.
One of the immediate impacts is the late filing penalty under Section 234F. Apart from this, you may also have to pay interest on any unpaid tax amount. More importantly, delays can affect your ability to carry forward certain losses, which can be useful for reducing future tax liability.
Late filing can also slow down your refund process. If you are eligible for a refund, filing late means waiting longer to receive your money. In some cases, repeated delays or non filing can attract notices from the tax department, creating unnecessary stress.
Penalties Under Section 234F and Other Charges
Section 234F clearly defines the late filing penalty for income tax returns in India. If you file your ITR after the due date but before 31st December of the assessment year, a late fee of up to five thousand rupees may be applicable. If you file after 31st December, the penalty can go up to ten thousand rupees.
For taxpayers with lower income, there may be some relief, but the penalty still applies. Along with this, interest under Section 234A may be charged on the outstanding tax amount. This interest continues to accumulate until the tax is paid in full.
These penalties and interest charges can increase your financial burden unnecessarily. This is why timely filing is always the better option.
Impact of Late Filing on Refunds and Loss Carry Forward
One of the most overlooked consequences of late filing is the impact on financial benefits. If you are eligible for a tax refund, filing your return late can delay the process significantly. This means your money stays stuck with the tax department for a longer period.
Another important aspect is the inability to carry forward certain losses. For example, business losses or capital losses can usually be carried forward to offset future income, helping you reduce your tax liability. However, if you miss the filing deadline, you may lose this benefit entirely.
These factors highlight why timely ITR filing in India is not just about avoiding penalties but also about maximizing your financial advantages.
Why Timely ITR Filing Is Important
Filing your ITR on time provides multiple benefits that go beyond compliance. It helps you maintain a clear financial record, which is essential for loan approvals, visa applications, and financial planning.
Timely filing also reduces stress. Instead of rushing at the last moment, you get enough time to gather documents, review your details, and file accurately. This minimizes the chances of errors and ensures that your return is processed smoothly.
Moreover, early filing allows you to receive refunds faster and plan your finances better. It gives you clarity about your tax position and helps you make informed decisions for the future.
Common Reasons People Delay ITR Filing
Despite knowing the importance of filing on time, many taxpayers delay the process. One common reason is lack of awareness about the deadline or filing requirements. Others find the process confusing and postpone it until it becomes urgent.
In some cases, people struggle with organizing their financial documents or understanding which ITR form to use. Freelancers and small business owners often face additional challenges due to multiple income sources and expense tracking.
Procrastination also plays a major role. Many individuals assume they will handle it later, only to realize they have missed the deadline. This leads to unnecessary penalties and last minute stress.
How Professional Help Can Simplify the Process
This is where professional tax filing services can make a significant difference. Instead of dealing with confusion and errors, you can rely on experts who understand the process thoroughly.
LIT NEXUS offers reliable and efficient tax filing services designed to make ITR filing in India simple and hassle free. With professional support, you can ensure that your return is filed accurately and on time. Experts can also help you identify deductions, optimize your tax liability, and avoid common mistakes.
For freelancers, business owners, and individuals with complex financial situations, professional assistance is especially valuable. It not only saves time but also provides peace of mind knowing that your taxes are handled correctly.
Conclusion
Understanding the last date to file ITR in India and the penalties for late filing is essential for every taxpayer. Missing the deadline can lead to late fees, interest charges, delayed refunds, and loss of financial benefits. On the other hand, timely filing ensures compliance, reduces stress, and helps you manage your finances effectively.
If you want to avoid penalties and make the process smooth, seeking professional support can be a smart decision. LIT NEXUS helps you stay compliant, accurate, and stress free during tax season. Filing your ITR on time is not just a legal requirement, it is a step towards better financial planning and long term stability.
Take control of your taxes today and ensure you never miss a deadline again.
Post a comment
Related Posts
What Happens If You Ignore Your Business Finances?
Introduction Running a business involves countless responsibilities. From managing customers and employees to handling sales,…
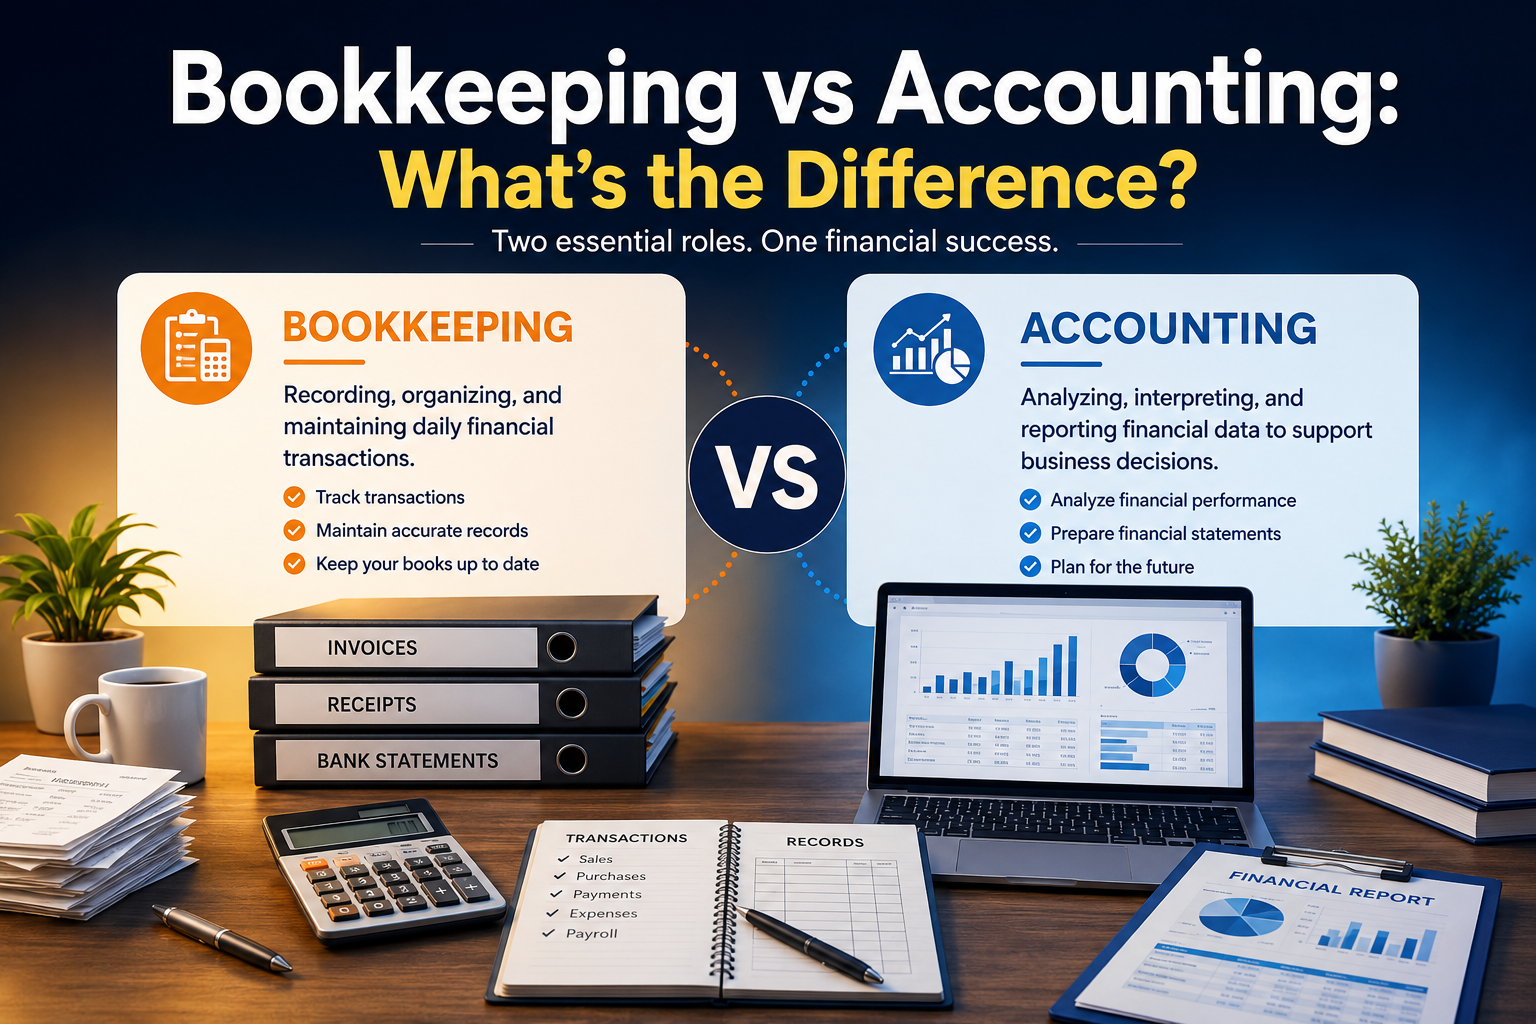
Bookkeeping vs. Accounting: What’s the Difference?
Managing your business finances is one of the most important responsibilities of being a business…
Why Clean Books Matter During Tax Season
Introduction For many business owners, tax season is one of the most stressful times of…