Demos
 Colors
 Docs
 Support




Introduction
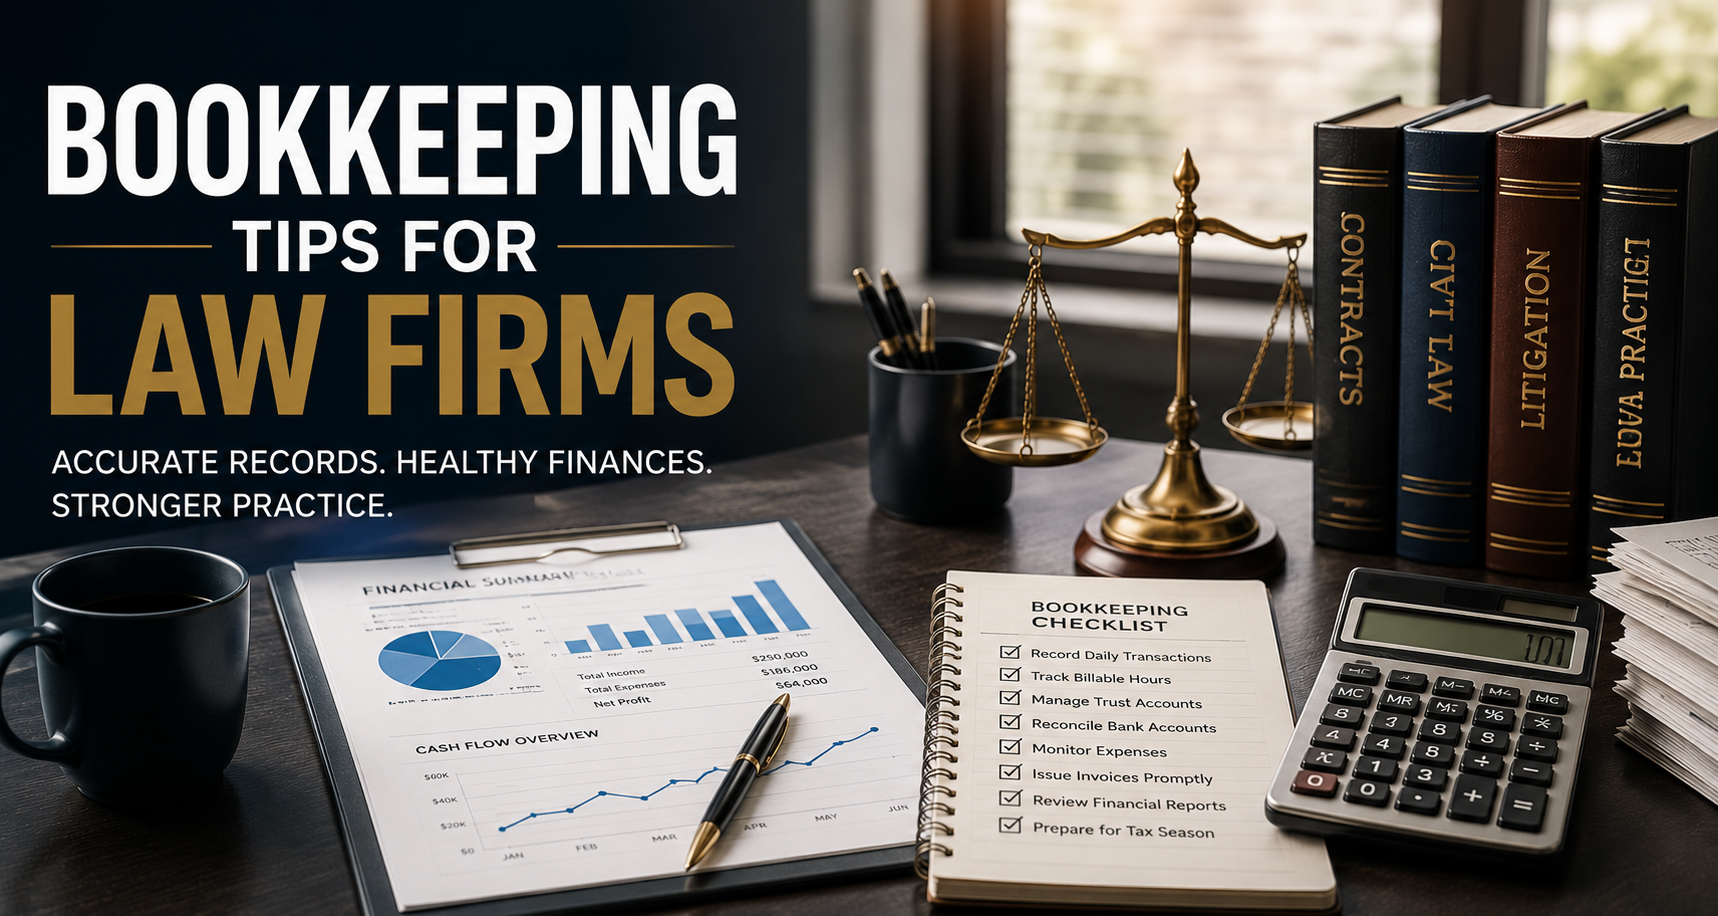
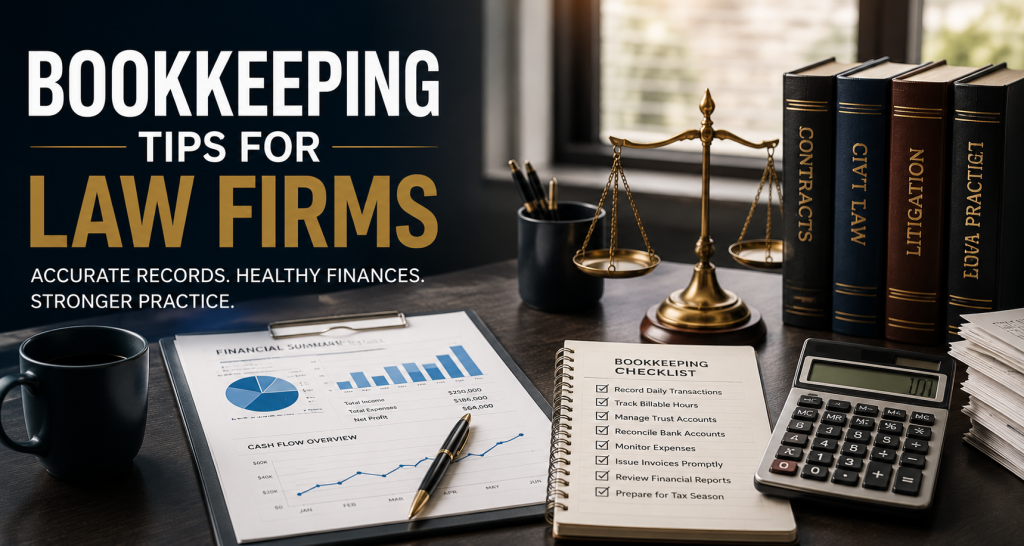
Running a successful law firm requires more than delivering exceptional legal services. Behind every profitable practice is a well-organized financial system that ensures accurate bookkeeping, healthy cash flow, regulatory compliance, and informed business decisions. Whether you operate as a solo attorney or manage a growing legal practice, maintaining accurate financial records is essential for long-term success.
Unlike many other businesses, law firms often deal with trust accounts, client retainers, billable hours, court expenses, and complex invoicing structures. Without proper bookkeeping, these financial responsibilities can quickly become overwhelming and increase the risk of costly errors.
By following sound bookkeeping practices, law firms can improve financial management, reduce administrative stress, and focus more on serving clients.
Why Bookkeeping Is Essential for Law Firms
Bookkeeping provides a clear picture of a law firm’s financial health. Accurate financial records help firms monitor revenue, manage operating expenses, prepare for tax obligations, and ensure compliance with legal and accounting regulations.
Reliable bookkeeping also supports better budgeting, strategic planning, and profitability analysis. When financial records are updated consistently, attorneys can make informed business decisions based on real-time financial data instead of assumptions.
A strong bookkeeping system ultimately contributes to greater operational efficiency and financial stability.
Keep Personal and Business Finances Separate
One of the most important bookkeeping practices for any law firm is maintaining separate business and personal financial accounts.
Using dedicated business bank accounts and credit cards simplifies bookkeeping, improves financial transparency, and reduces confusion during tax preparation. It also strengthens compliance and provides a more accurate view of the firm’s financial performance.
Separating finances from the beginning helps avoid unnecessary accounting complications later.
Maintain Accurate Trust Account Records
Many law firms manage client trust accounts or retainers, making accurate recordkeeping especially important.
Funds held on behalf of clients should always be tracked separately from the firm’s operating funds. Every deposit, withdrawal, and transfer should be properly documented to ensure complete transparency and compliance with applicable legal and professional standards.
Regular reconciliation of trust accounts helps identify discrepancies early and protects both the firm and its clients.
Record Every Financial Transaction
Every payment received, invoice issued, expense incurred, and reimbursement processed should be recorded promptly.
Delaying bookkeeping often leads to missing transactions, inaccurate financial reports, and unnecessary complications during tax season.
Maintaining current financial records allows law firms to monitor profitability and maintain confidence in the accuracy of their accounting information.
Track Billable Hours Accurately
Billable hours are one of the primary revenue sources for many law firms. Accurate time tracking ensures clients are billed fairly while helping the firm maximize revenue.
Integrating time tracking with accounting software simplifies invoicing and reduces the likelihood of missed billable work.
Consistent monitoring of billable hours also provides valuable insights into staff productivity and overall business performance.
Organize Client Invoices and Payments
A structured invoicing process improves cash flow and reduces outstanding receivables.
Invoices should be issued promptly with clear payment terms and accurate descriptions of legal services provided. Monitoring unpaid invoices regularly enables firms to follow up with clients before overdue payments become significant collection issues.
Efficient invoice management contributes to healthier cash flow and more predictable revenue.
Monitor Operating Expenses
Law firms incur a variety of operating expenses, including office rent, employee salaries, legal research tools, software subscriptions, court filing fees, insurance, and professional memberships.
Tracking these expenses consistently helps identify unnecessary spending and supports more effective budgeting.
Understanding where money is being spent allows firms to improve profitability without compromising service quality.
Reconcile Bank Accounts Every Month
Monthly bank reconciliation ensures that accounting records match bank statements accurately.
This process helps identify duplicate entries, missing transactions, unauthorized charges, and recording errors before they affect financial reporting.
Regular reconciliation provides confidence that the firm’s financial information remains accurate and reliable.
Use Cloud-Based Accounting Software
Modern accounting software has transformed bookkeeping for professional service firms.
Cloud-based accounting platforms allow law firms to access financial information securely from anywhere while automating invoicing, expense tracking, financial reporting, and bank reconciliation.
These tools reduce manual work, improve accuracy, and make collaboration with accountants significantly easier.
Prepare Financial Reports Regularly
Financial reports provide valuable insight into the overall performance of a law firm.
Profit and Loss Statements help measure profitability, Balance Sheets provide an overview of assets and liabilities, and Cash Flow Statements reveal how money moves throughout the business.
Reviewing these reports each month enables firm owners to identify trends, evaluate performance, and make informed strategic decisions.
Stay Prepared for Tax Season
Accurate bookkeeping throughout the year makes tax preparation far more efficient.
Well-organized financial records ensure that income, expenses, deductions, payroll information, and supporting documentation are readily available when tax deadlines approach.
Maintaining updated books also reduces the risk of errors, penalties, and last-minute stress.
Protect Confidential Financial Information
Law firms handle sensitive financial and client information that requires strong security measures.
Accounting records should be protected using secure cloud storage, encrypted systems, strong passwords, and regular data backups. Access to financial information should be limited to authorized personnel only.
Maintaining secure bookkeeping practices protects client confidentiality and strengthens overall business integrity.
Consider Outsourcing Your Bookkeeping
As legal practices grow, bookkeeping responsibilities become increasingly complex and time-consuming.
Outsourcing bookkeeping to experienced professionals allows attorneys and legal staff to focus on serving clients instead of managing financial records.
Professional bookkeeping services ensure accurate reporting, timely reconciliations, payroll management, tax readiness, and ongoing financial compliance while reducing administrative workload.
This approach improves efficiency and provides greater confidence in the firm’s financial operations.
Conclusion
Effective bookkeeping is a critical component of every successful law firm. Accurate financial records improve cash flow management, strengthen compliance, simplify tax preparation, and provide the financial clarity needed for informed business decisions.
By maintaining organized records, tracking billable hours, managing trust accounts carefully, reconciling bank accounts regularly, and leveraging professional bookkeeping support, law firms can build a strong financial foundation for sustainable growth.
Partnering with experienced bookkeeping professionals allows legal practitioners to spend less time managing finances and more time delivering outstanding legal services to their clients.
Post a comment
Related Posts
What Happens If You Ignore Your Business Finances?
Introduction Running a business involves countless responsibilities. From managing customers and employees to handling sales,…
Bookkeeping vs. Accounting: What’s the Difference?
Managing your business finances is one of the most important responsibilities of being a business…
Why Clean Books Matter During Tax Season
Introduction For many business owners, tax season is one of the most stressful times of…